Ava Finance

Screenshots
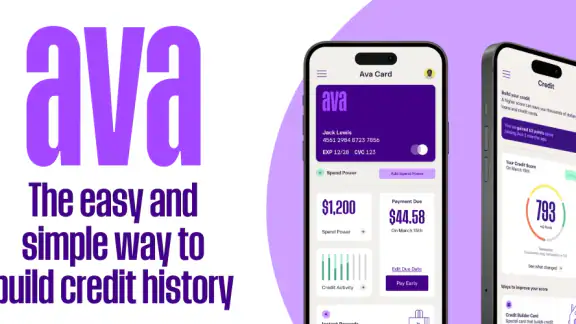
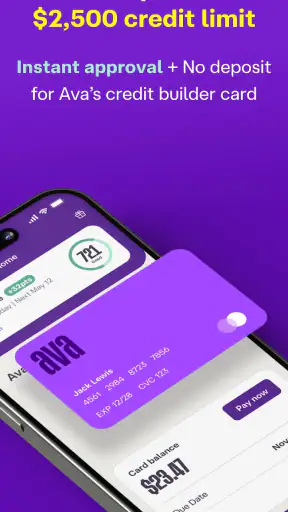
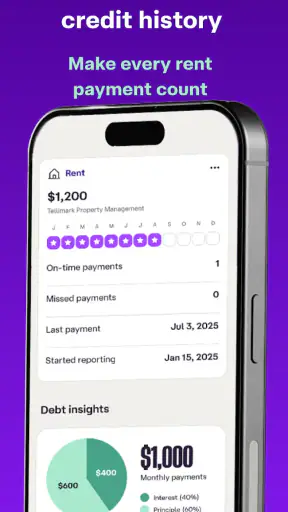
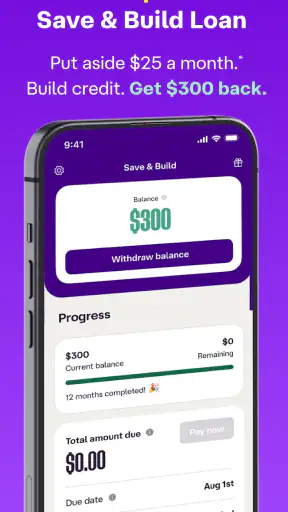
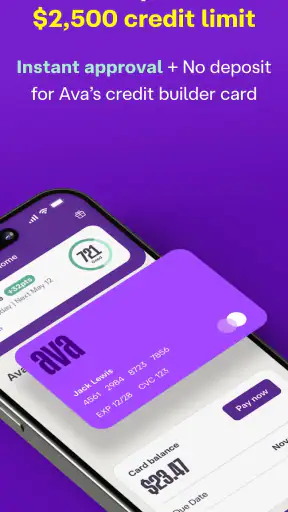
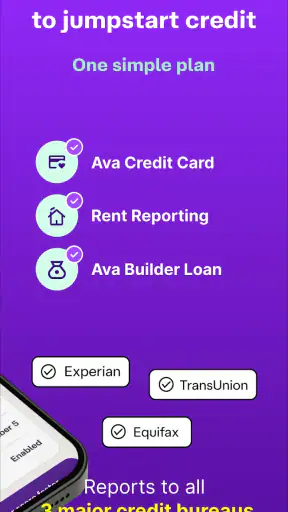
Details
- Rating
- 1.69K reviews
- Version
- 5.1.6626
- Developer
- Ava Finance, Inc.
Analysis by Norviv
I approached Ava Finance as a practical credit-building app rather than as a complete replacement for a bank. Its purpose is easy to understand: it gives people a focused way to work on credit while keeping the experience inside a finance app. That narrow focus is part of its appeal. You are not opening it to browse investments, trade shares, or manage every bill in one place. You are opening it because credit matters and you want a more guided route than simply waiting for your financial history to improve on its own.
My overall impression is positive, especially for someone who feels lost when dealing with credit for the first time. Ava Finance, Inc. has built an app that feels approachable enough for everyday use, and the strong public response supports that impression: it holds a 4.7 average from around 17 thousand ratings, with roughly 1.7 thousand written reviews. It is free to install and aimed at Everyone, which makes the first step feel low-risk, although using any finance product still deserves careful attention to its terms and your own budget.
How Ava feels when you use it regularly
When I use Ava as part of a regular routine, I find it helpful to decide in advance what I want to check, rather than opening a finance app whenever money worries surface. That small boundary makes it easier to distinguish a useful progress review from anxious checking, and it sets up a closer look at how I judge trust and personal control in the sections that follow.
A quick start, with expectations kept realistic
The first thing I would tell a friend is not to confuse a quick app experience with instant credit improvement. The interface can make it easier to begin, but credit history develops through ongoing financial behavior. Ava is useful because it turns an abstract goal into something you can revisit, rather than because it promises a dramatic result after one session.
In normal use, the speed you notice most is the speed of understanding. A good finance app should help you answer basic questions without sending you through a maze, and Ava’s focused purpose works in its favor. The app summary, “Ava - Build Credit Fast,” sets a direct expectation, but I would still treat “fast” as a description of the intended journey, not a guarantee that every user will see the same outcome immediately.
The app has passed the point of being an obscure experiment. It has more than half a million installs, which suggests that many people are willing to try this particular approach to credit. That does not prove that it will suit every financial situation, but it does make the app feel like an established option rather than something I would install without checking carefully.
What happens during heavier financial use
The moments that deserve the most patience are not necessarily the moments when you open the app. They are the moments when you are reviewing your credit-building activity, checking details, or trying to understand what an action means for your wider finances. Financial apps are judged differently from entertainment apps: a small delay is usually tolerable, but confusion at the wrong moment can lead to a poor decision.
Stories Picked for You

Life360 Works Better When Your Household Agrees on What to Share

YouVersion Bible Fits Scripture into Everyday Phone Routines

Matchington Mansion Review: Match-Three Puzzles With a Place to Restore

Android Auto Shows Why Safer Driving Software Does Less

Google Find Hub Runs on Shared Devices and Quiet Trust

Sygic GPS Navigation: The Ultimate Offline Travel Companion
I would use Ava in short, deliberate sessions instead of leaving it open while trying to organize an entire household budget. That workflow keeps the app’s role clear. For example, imagine someone preparing to rent an apartment. They could use Ava as one part of a longer plan, checking their credit-building progress and making sure the related commitment fits alongside rent, utilities, food, and existing repayments. The useful habit is to review the app before making a decision, not to treat the app itself as permission to take on more debt.
This is also where a focused credit app differs from a general budgeting tool. A budgeting app may be better for categorizing spending across accounts, while Ava is more relevant when the main question is, “What am I doing to establish or improve my credit?” I would not expect it to replace a full view of cash flow. Its strength is concentration, and concentration inevitably means a narrower picture.
Stability matters more than flashy performance
For this type of product, stability is more important than animation, visual effects, or an especially elaborate dashboard. Ava does not need to feel exciting; it needs to feel dependable when I am checking a financial detail. The current version is 5.1.6626, so the app is clearly maintained as an ongoing product rather than left in its original release state. It first appeared on May 10, 2021, giving it several years of history as a finance service.
That history makes me more comfortable recommending it for routine checking, but I would still keep normal financial-app habits. I would read each screen before confirming anything, save important account information separately, and avoid making a rushed decision simply because the app presents a next step clearly. A smooth interface can reduce friction, but it cannot decide whether a commitment is affordable for you.
Recovery is another practical concern. If you change phones, lose access to an account, or need to return after a break, the important question is whether you can calmly regain access and understand your current position. I would prepare for that by keeping contact details current and retaining any relevant records outside the app. That is not a criticism unique to Ava; it is sensible behavior for any service connected to personal finances.
Device limits and everyday practicality
Ava supports devices running Android 9 or later, which gives it a reasonably broad reach while still excluding older phones. If you use an older handset, the operating-system requirement is the first compatibility check I would make before planning around the app. On a supported device, I would expect the basic experience to be more comfortable when the phone has enough free storage and is running normally, but I would not judge a finance app by demanding the same performance as a simple calculator.
Resource demands are best considered in context. This is not an app I would open continuously for hours. Most people will use it briefly to review information or complete a financial task, so the more important practical concern is whether it remains understandable and responsive during those short sessions. If your phone is old, crowded with apps, or frequently low on memory, any finance app can feel less pleasant even when the app itself is well designed.
I also prefer using a stable connection when checking important information. A finance app is not the place to guess whether a screen has fully updated. If a page appears incomplete or a confirmation takes longer than expected, I would wait and verify the result rather than tapping repeatedly. That small habit helps avoid duplicate actions and is particularly worthwhile when the task affects your financial routine.
The trade-off between guidance and independence
The main value I see in Ava is guidance. People who have never built credit, or who have been unsure how to start, may appreciate having a dedicated place to focus on the process. The app can act as a reminder that credit is something to manage deliberately rather than something that happens in the background.
The trade-off is that guidance can feel restrictive if you already have a well-developed financial system. Someone who tracks several cards, loans, savings goals, investments, and household accounts may prefer a banking app or a comprehensive money manager that brings everything together. Ava is not the choice I would make for a complete financial command center. I would use it alongside those tools if the specific credit-building purpose filled a gap.
There is another important distinction: building credit is not the same as repairing every financial problem. If your priority is paying down expensive debt, disputing an error, creating an emergency fund, or learning how to control irregular income, a credit-focused app may not be the best first tool. Ava can fit into a broader plan, but it should not distract from overdue obligations or basic affordability.
Three practical ways I would use it
First, I would use Ava as a scheduled review point. Rather than checking it repeatedly out of anxiety, I would choose a regular moment to look at my progress and compare that with my actual budget. This turns the app into a habit-building aid instead of a source of constant notifications or speculation.
Second, I would pair it with a separate spending overview. I would track everyday cash flow somewhere that shows bills and discretionary spending, then use Ava for the credit-specific part of the plan. This separation is useful because it prevents a narrow credit goal from hiding the bigger question of whether monthly commitments are manageable.
Third, I would use it before a major application, but not as the only preparation. If I were considering a rental application or another credit-related decision, I would review my finances, check that my personal information is current, and then use Ava as one reference point. The non-obvious benefit here is discipline: the app becomes part of a checklist, not a magic prediction of approval.
Who should consider Ava, and who should skip it
I think Ava is a good match for a beginner who wants a dedicated credit-building experience and prefers a simpler focus over a crowded financial dashboard. It may also suit someone who has ignored credit for a long time and needs a clear routine to get started. The free price makes trying it easier, and the Everyone rating makes it broadly approachable from an age-classification perspective.
I would be more cautious about recommending it to someone who already has a strong credit strategy and wants advanced control over every financial account. I would also suggest skipping it as a first step if your budget is unstable or you are struggling with essential bills. In that situation, the priority should be financial breathing room. A credit goal is worthwhile, but not at the cost of taking on a commitment you cannot comfortably maintain.
People who dislike checking financial apps regularly may also find the experience less useful. Credit-building is not a one-time download. The app can organize the process, but the user still has to pay attention, understand the consequences of each action, and keep the wider budget in view. If you want a completely automatic solution that requires no review, Ava is unlikely to feel satisfying.
My performance verdict
From a performance perspective, Ava’s strongest quality is its focused design rather than raw speed. I would expect the app to feel most useful in short, purposeful sessions, when I am checking credit-related information and deciding what to do next. Its long-running presence, current version, and large install base give it the profile of a maintained finance app, while its Android 9 requirement keeps it accessible to many but not every device.
The limitations are equally clear. No app can remove the time and responsibility involved in building credit, and a focused credit tool cannot replace a full budget, debt plan, or bank relationship. The safest approach is to treat Ava as one component of a larger financial routine. Read carefully, check affordability outside the app, and keep independent records for important details.
After using it with that mindset, I would recommend Ava to a friend who wants a straightforward place to work on credit and needs more structure than a general banking app provides. I would not recommend relying on it alone for every money decision. Its real advantage is turning credit-building into a visible routine without pretending that the app can do the financial work for you. That balance is what makes it worth considering: approachable enough for a newcomer, focused enough to be useful, and limited enough that you should understand exactly where it fits in your wider plan.
Frequently Asked Questions
01What is Ava Finance, and what can I use it for?
Ava Finance is a personal finance app designed to help users organize and monitor their money from a mobile device. Depending on the services available in your region, it may provide tools for tracking spending, reviewing financial activity, setting goals, managing budgets, or accessing related financial products. Before downloading, check the official description carefully because features, supported institutions, and account options can vary by country.
02Is Ava Finance safe to use with my personal or financial information?
Because a finance app may handle sensitive information, users should review Ava Finance’s privacy policy, security practices, and permissions before creating an account. Look for details about encryption, authentication, data sharing, and how information can be deleted. Use a strong, unique password and enable available security features. Avoid entering banking details through unofficial versions or links obtained from unknown websites.
03Does Ava Finance connect directly to my bank accounts or cards?
Ava Finance may offer account connections or financial tracking features, but availability depends on the country, supported banks, and the current version of the app. If linking an account is supported, the app should explain what information it can access and whether a third-party connection service is involved. Read the authorization screen carefully and remember that some institutions may not be compatible.
04Is Ava Finance free, or does it include subscriptions and additional charges?
The download price and the cost of using Ava Finance can differ. Some features may be free, while advanced tools, premium services, transactions, transfers, or financial products could involve subscription fees or other charges. Check the app-store listing and the in-app pricing pages before confirming payment. Also review renewal terms, trial periods, and cancellation instructions so you are not surprised by recurring billing.
05What should I do if Ava Finance does not work or I need help with my account?
If Ava Finance fails to load, cannot connect to an institution, or displays incorrect information, first update the app, check your internet connection, and review its service-status or help resources. For account, payment, or identity issues, contact official support through the app or the developer’s verified website. Do not share passwords, verification codes, or full financial credentials with anyone claiming to provide unofficial assistance.


